Stocks Versus Bonds Allocation for Your Goals
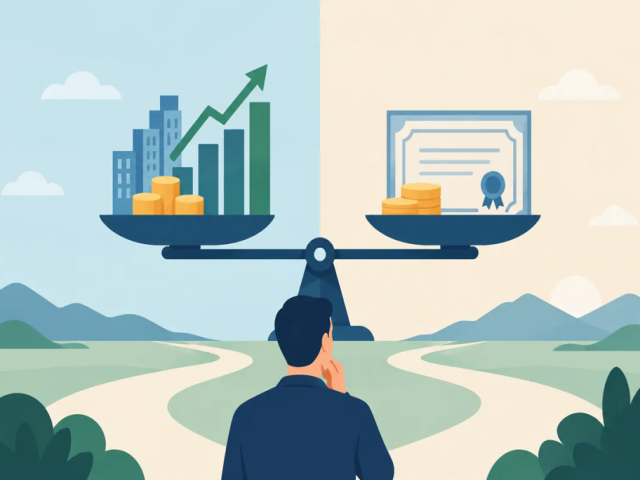
Learn how stocks versus bonds allocation can support growth, income, and stability, then build a portfolio aligned with your time horizon and risk level.
A portfolio can look successful on a screen and still be poorly positioned for the life you want to live. The real question behind stocks versus bonds allocation is not which asset class is “better.” It is how much growth potential you need, how much market movement you can accept, and when you may need your money to work for you.
For investors seeking passive income and long-term financial well-being, the right mix can create a clearer path than chasing whichever market is making headlines. Stocks and bonds play different roles. Understanding those roles helps you make decisions with more confidence and less emotion when prices move.
What Stocks Bring to a Portfolio
Stocks represent ownership in companies. When you invest in equities, you are participating in the potential growth of businesses as they expand revenues, introduce products, gain customers, and generate profits. Over long periods, this growth potential is why stocks are commonly used as the engine of a wealth-building portfolio.
The trade-off is volatility. Stock values can rise quickly, but they can also decline sharply during economic uncertainty, geopolitical events, changing interest rates, or company-specific problems. A strong long-term opportunity can still experience uncomfortable short-term drops.
That does not make stocks unsuitable. It means stock exposure should match your timeline and your ability to remain invested through market cycles. If your goal is years away, such as retirement, building business capital, or creating future family security, you may have more time for market growth to develop. If you expect to need funds soon, heavy stock exposure may create pressure to sell at the wrong moment.
Stocks can also support income through dividends, although dividend payments are never guaranteed and can change. For many investors, the larger role of equities is capital appreciation: giving assets the chance to increase in value over time.
What Bonds Bring to a Portfolio
Bonds are generally loans made to governments, municipalities, or companies. In exchange, the issuer promises to make interest payments and return the principal at maturity, assuming it remains able to meet its obligations. This makes bonds a different kind of portfolio tool.
A bond allocation can provide a steadier source of income and may reduce the overall swings of a portfolio. When stock markets become unsettled, high-quality bonds can sometimes help cushion declines. They are not risk-free, but they are often used to bring structure and stability to an investment plan.
Bonds have their own challenges. Rising interest rates can push the market value of existing bonds down. Lower-quality issuers may face credit risk. Inflation can reduce the purchasing power of fixed interest payments. And in some environments, bonds may deliver modest returns compared with equities.
The purpose of bonds is not necessarily to outperform stocks. Their value is often in helping investors stay committed to a strategy when the stock market becomes difficult to watch.
Stocks Versus Bonds Allocation Starts With Timing
A sensible allocation begins with the date attached to your goal. This matters more than a popular rule of thumb or a one-size-fits-all percentage.
An investor building wealth for a goal 15 or 20 years away may choose a portfolio weighted more heavily toward stocks. There is time to pursue growth and potentially recover from normal market downturns. That investor still needs diversification, but the emphasis may reasonably be on long-term appreciation.
An investor saving for a home purchase within two years has a different problem. The priority is not maximizing upside. It is protecting funds that may soon be needed. A more conservative mix, including a larger bond or cash allocation, can reduce the chance that a market decline disrupts the purchase.
Many goals sit in the middle. A business owner may want accessible reserves while also investing for longer-term expansion. A working professional may be saving for a child’s education while building retirement assets. In these cases, separating money by purpose can be more useful than forcing every dollar into a single portfolio mix.
Your Risk Tolerance Is More Than a Questionnaire
Risk tolerance is often described as how you feel about losses. That is part of it, but it is not the whole picture. Your financial capacity for risk matters just as much.
Someone with stable income, a strong emergency fund, limited high-interest debt, and a long investment horizon may be able to accept more equity exposure than someone who relies on portfolio withdrawals for monthly expenses. Even a confident investor can be forced into bad decisions if they do not have enough liquidity outside the market.
Ask a direct question: if the stock portion of your portfolio fell substantially over several months, would you hold, invest more, or feel compelled to withdraw? Your honest answer can reveal whether an aggressive allocation is truly sustainable.
The best allocation is not the most exciting one. It is the one you can continue to follow through both optimism and uncertainty.
Three Allocation Approaches to Consider
There is no universal formula, but these broad approaches show how stocks and bonds can serve different priorities.
Growth-focused allocation
A growth-focused investor may hold a larger share of stocks and a smaller share of bonds. This approach fits investors with long time horizons and a willingness to tolerate larger account fluctuations in pursuit of higher long-term return potential. It is often most appropriate when near-term withdrawals are not expected.
Balanced allocation
A balanced mix gives meaningful space to both stocks and bonds. The stock portion seeks growth, while the bond portion can contribute income and moderation during volatile periods. This approach may suit investors who want progress without placing their entire plan on the direction of the equity market.
Income and stability-focused allocation
An investor approaching a planned purchase, retirement withdrawals, or a shorter financial objective may place more emphasis on bonds and other lower-volatility holdings. The goal is to create a more dependable base, although the portfolio may have less potential for rapid long-term growth and may still be affected by inflation or interest-rate changes.
These approaches are starting points, not promises. The right percentages depend on your goals, existing assets, income needs, tax situation, and comfort with uncertainty.
Diversification Matters Inside Each Category
Choosing a stock and bond percentage is only the first decision. A portfolio concentrated in a few companies, one industry, or one country can carry more risk than the headline allocation suggests. Similarly, a bond portfolio focused only on one issuer type or maturity range may be more vulnerable than expected.
Diversification spreads exposure across different holdings and market drivers. Equities may include large and smaller companies, domestic and international markets, and multiple sectors. Bonds may vary by issuer quality, maturity, and type. The objective is not to eliminate risk. It is to avoid making your financial future depend too heavily on one event, one company, or one market segment.
For investors who do not want to monitor markets every day, managed investing can make this process more accessible. A platform such as Budrigantrade can help investors pursue professionally monitored market exposure while maintaining visibility into their portfolio activity. Professional oversight does not remove market risk, but it can offer a more organized approach than making emotional changes based on daily headlines.
Rebalancing Keeps Your Plan From Drifting
A portfolio can move away from its intended allocation without you making a single new investment. If stocks rise faster than bonds, the stock percentage grows. Your portfolio may become more aggressive than you originally planned. If equities decline, the opposite can happen.
Rebalancing means reviewing the mix periodically and bringing it back toward your target. This may involve directing new deposits toward the underweighted asset class or adjusting holdings when the difference becomes meaningful. It is a disciplined process that can prevent market momentum from quietly rewriting your risk level.
Avoid reacting to every small price change. Monthly market noise does not necessarily call for a portfolio overhaul. A scheduled review, combined with a review after major life changes, is usually more practical. A new child, career move, business sale, upcoming purchase, or change in income needs can all justify reassessing your allocation.
Build Around the Life You Want to Fund
Stocks offer the potential to grow your capital. Bonds can provide income, balance, and a measure of stability. Neither asset class needs to win a contest for your portfolio to work. Their value comes from the role each plays in supporting your objectives.
Set the allocation around your timeline, keep enough liquidity for near-term needs, and let your level of risk reflect reality rather than ambition alone. The most useful portfolio is one that gives your money a clear job today while keeping your longer-term opportunities within reach.
Recent Posts
-
A Small Business Cash Reserve Example That Works
23 Sep 2026
-
Retirement Planning That Builds Real Flexibility
23 Sep 2026
-
15 Best Investor Due Diligence Questions
23 Sep 2026
-
15 Best Investor Due Diligence Questions
23 Sep 2026
-
Investment Platform Security Review Made Simple
19 Sep 2026
-
Best Portfolio Rebalancing for Lasting Growth
19 Sep 2026
-
Crypto Custody Versus Exchange Wallets Explained
19 Sep 2026
-
AI Investing: A Smarter Way to Build Wealth
14 Sep 2026
-
How to Set Investment Goals That Fit Your Life
14 Sep 2026
-
Retirement Income Guide for Lasting Cash Flow
14 Sep 2026
-
-
Investment Taxes: Keep More of What You Earn
10 Sep 2026
-
How Are Crypto Gains Taxed for U.S. Investors?
10 Sep 2026
-
How to Secure Crypto Deposits Without Mistakes
10 Sep 2026
-
A Clear Guide to Investment Risk Tolerance
10 Sep 2026